


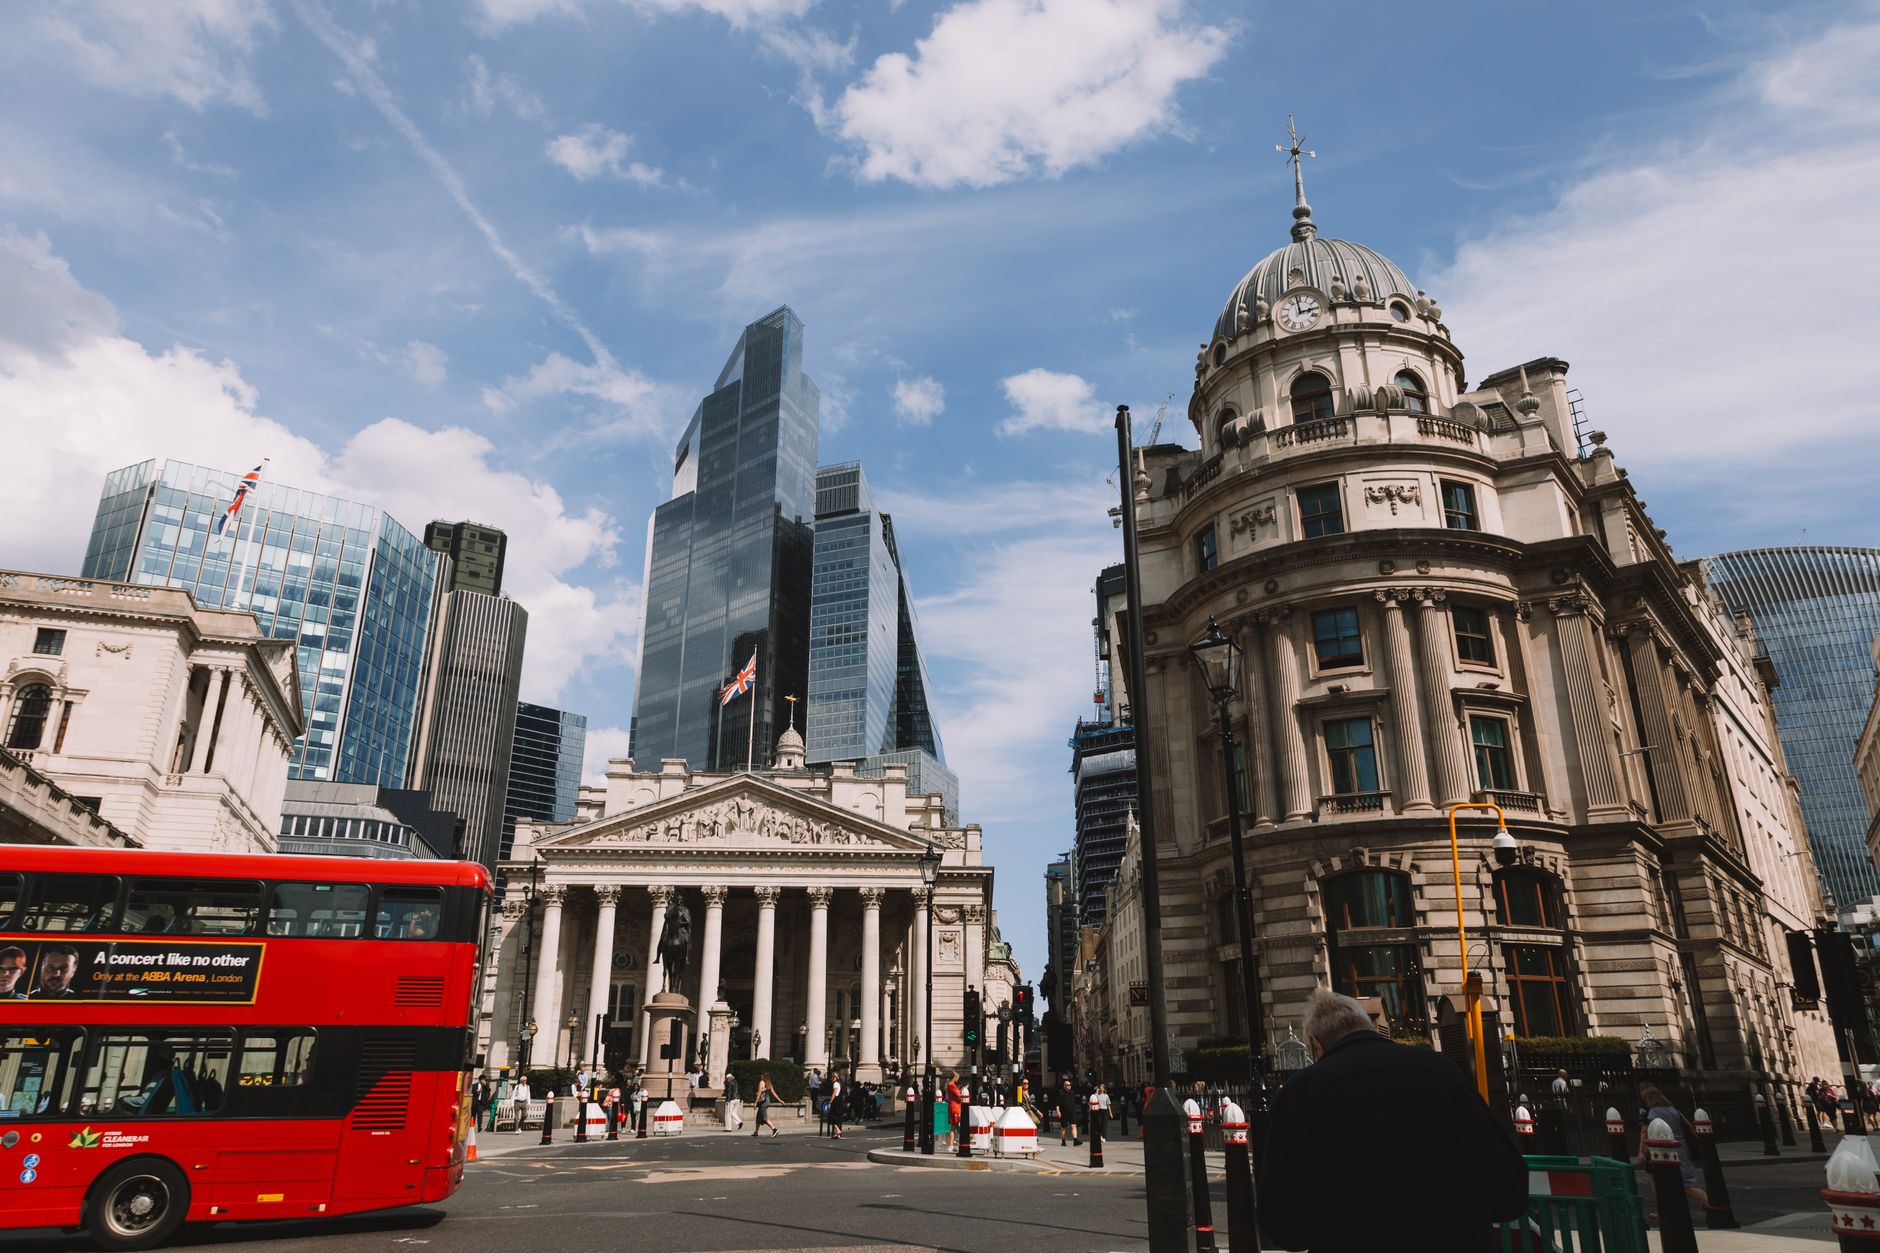
Policymakers at the Bank of England are widely expected to announce an increase in interest rates on Thursday, marking the first such hike in more than three years. Financial analysts are predicting the benchmark rate will climb from its current level of 3.75% to 4%. The decision follows a period where the Bank’s Monetary Policy Committee (MPC) has kept rates unchanged at its last six meetings, having previously fallen from a 2023-24 peak of 5.25%.
The move is largely being driven by concerns over rising inflation, which has been primarily pushed by the increasing costs of petrol and diesel. Recent data indicates that the Consumer Prices Index (CPI) reached 3.5% in the year to September 2026, marking an increase from 3.1% the previous month. This figure remains significantly higher than the central bank's 2% target. Furthermore, ongoing international instability, particularly the conflict involving Iran, has continued to exert pressure on energy and fuel prices, filtering through to the broader UK economy.
The announcement is scheduled for 12:00 GMT on Thursday. Market observers are particularly focused on any guidance from the MPC regarding the future trajectory of interest rates. Chris Cheverall, head of UK at trading platform CMC Markets, noted that the discussion is shifting away from the immediate prospect of a 4% rate and toward the strategy that follows. He explained that the Bank faces the difficult challenge of balancing persistent inflation against a sharp weakening in the economic growth outlook.
The potential rate hike will have direct implications for household finances, particularly for mortgage holders. According to industry calculations, a 0.25 percentage point increase would result in an additional £31 in monthly repayments for those on tracker mortgages. Individuals on variable rate deals may also see an increase, though this depends on how individual lenders choose to react to the Bank's decision. Fixed-rate mortgage holders are not immediately impacted, though lenders have reportedly already factored these expected rate increases into current quotes for new deals.
Financial information service Moneyfacts indicated that as of 4 November, the average two-year fixed residential mortgage rate was 5.96%, while five-year rates stood at 5.99%. Consequently, borrowers reaching the end of their existing fixed-term deals are likely to face substantially higher monthly payments compared to previous years. Data from the broker L&C suggested that borrowers renewing a £200,000 mortgage could see their annual repayments rise by nearly £5,000 compared to those who secured deals in 2021, when rates were significantly lower.
For some, the environment has prompted a shift in strategy. Rachel Springall of Moneyfacts noted that the decision between tracker and fixed deals depends heavily on a borrower's ability to withstand further potential fluctuations. While the hike poses challenges for those with debt, it may provide relief for savers, who could see the interest rates offered on their accounts improve as a result of the higher benchmark.
Ultimately, the Bank of England’s decision reflects the complex nature of the current economic landscape. Policymakers must weigh the impact of rising energy costs against the vulnerability of the UK economy, which remains deeply influenced by shifts in global events. As the country braces for potential price increases in domestic energy in January, the upcoming rate decision serves as a critical indicator of the Bank's strategy for managing the cost of living.





Comments