


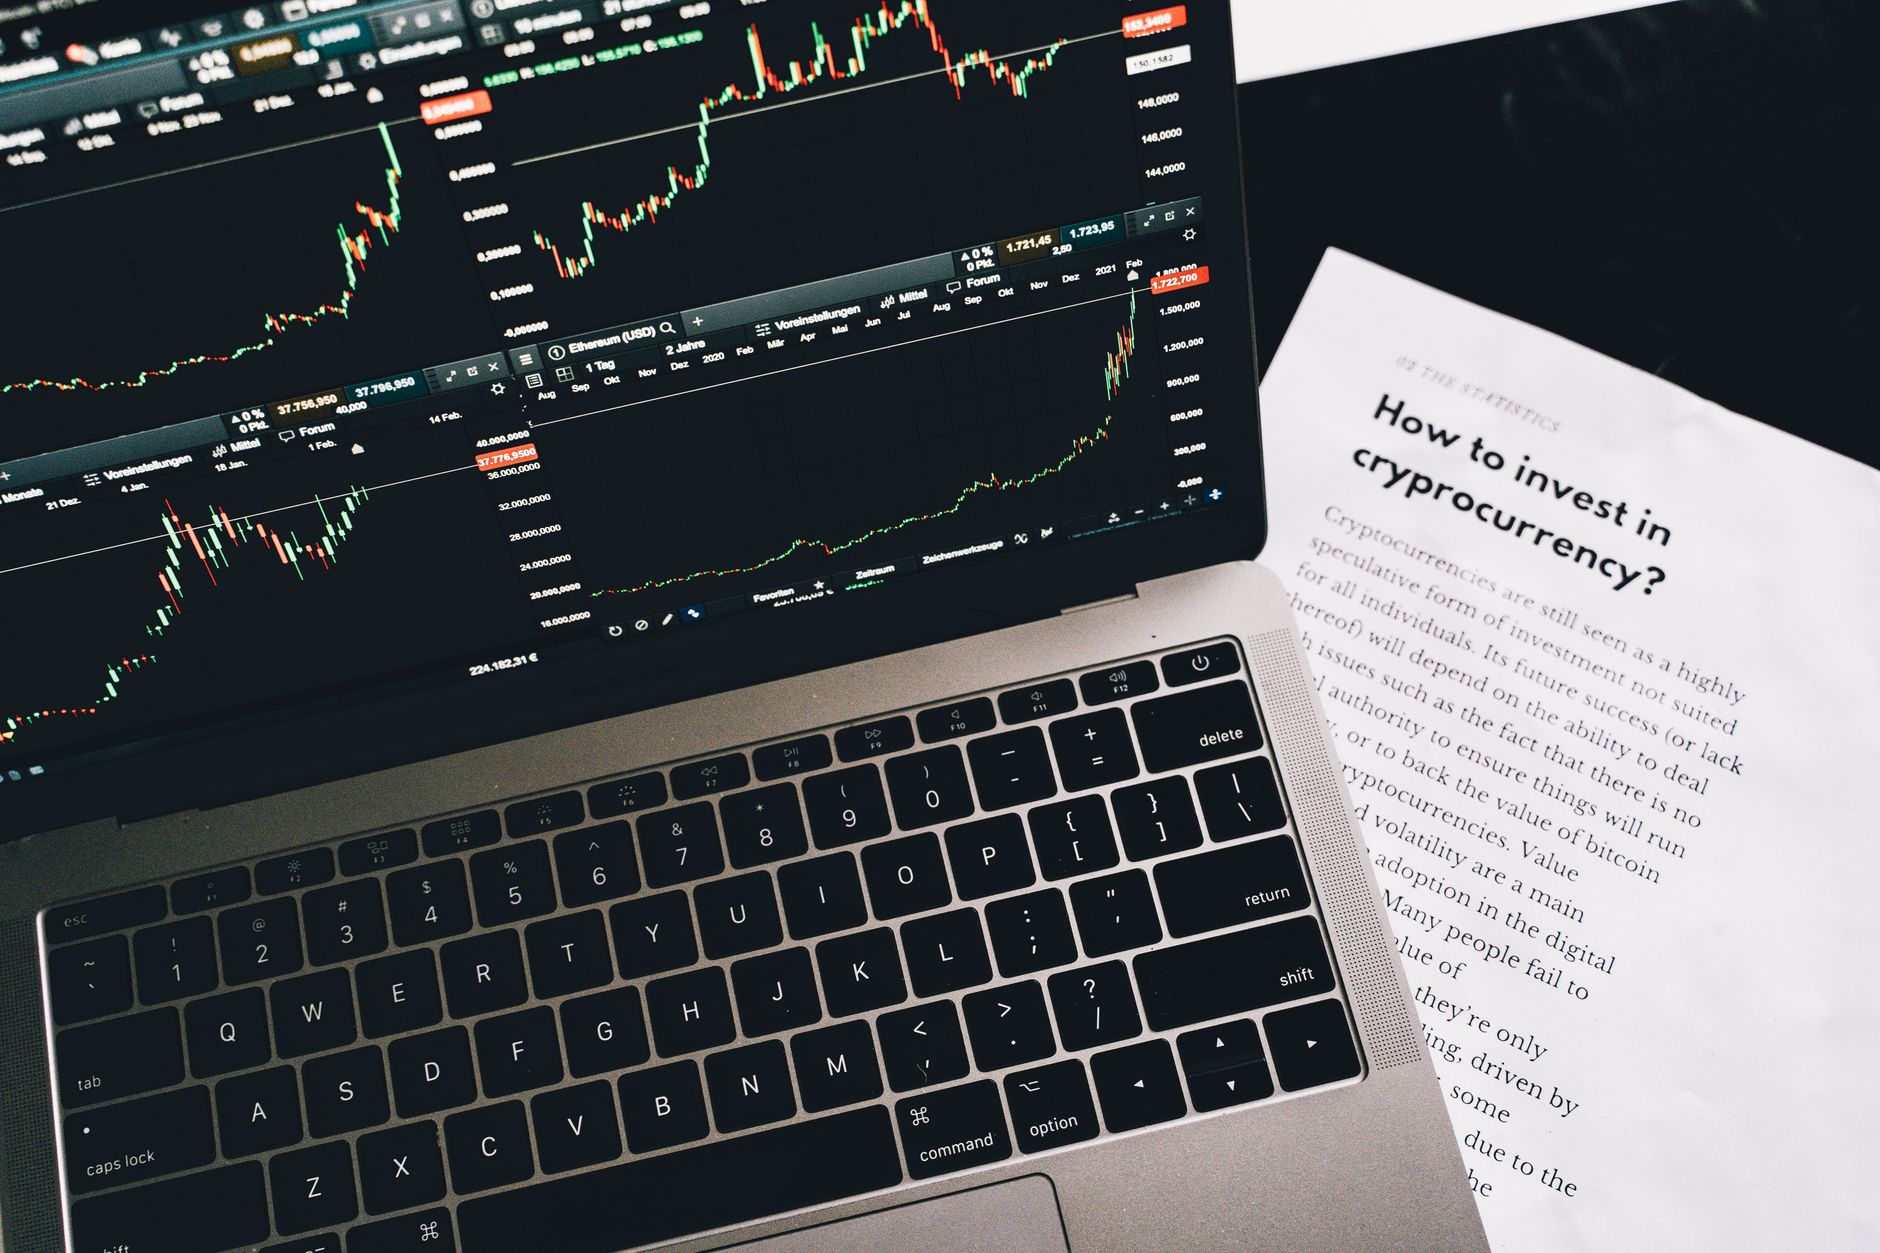
With Israel facing increasing international pressure over its military operations in Gaza and the expansion of settlements in the occupied West Bank, Prime Minister Benjamin Netanyahu has suggested that the nation should prepare to utilize cryptocurrency to circumvent potential future economic sanctions. Speaking during an interview with Israel’s Channel 10 just days before the upcoming general election, the Prime Minister argued that the country must develop alternative economic systems to bypass standard banking restrictions that could potentially lock the nation out of the international financial circuit.
Netanyahu emphasized that blockchain-based assets represent a possible solution for maintaining cross-border transactions should traditional banking channels be restricted. The Prime Minister noted that his proposal is partly motivated by a shifting geopolitical landscape, specifically expressing concerns regarding future American military financing. According to Netanyahu, the current levels of financial and military support from Washington may not be sustainable, and the country should prepare for a future where support from the United States might diminish.
The proposal has been met with immediate resistance from within Israel’s financial and political establishment. The Bank of Israel, the nation’s central bank, has officially rejected the plan. Meanwhile, various opposition parties have criticized the suggestion, characterizing it as a reckless vision that would only serve to increase the country's isolation rather than mitigate it. Critics point out that despite Netanyahu's rhetoric, the domestic and international financial systems are deeply integrated, and digital currencies are not currently equipped to handle the scale of Israel's national economic needs.
The backdrop for this proposal includes significant global concern regarding Israel’s policies, which have drawn sanctions from several major economies. Last month, a coalition of at least 12 nations, including the United Kingdom, pledged coordinated measures against settlement activity. Furthermore, the European Union has moved to sanction specific individuals and groups linked to settlements, while countries like the Netherlands, Spain, and Ireland have introduced restrictions or bans on goods originating from these areas. While the Israeli banking system has not yet been the primary target of these sanctions, the threat of financial exclusion has become a central point of the current national debate.
Financial experts note that while cryptocurrencies allow for direct transfers between digital wallets—thereby bypassing traditional banks—they are far from a panacea. Even if businesses were to attempt to use Bitcoin or stablecoins to pay overseas suppliers, the underlying transactions would still be subject to international regulations. Financial isolation is designed to penalize not just the primary entity but also third parties that engage in trade with designated actors, meaning that shifting to a digital ledger would not necessarily grant immunity from legal repercussions or compliance requirements.
Additionally, Israel's economy remains heavily reliant on global trade, particularly within the technology and defense sectors, which require complex supply chains and foreign components. Analysts suggest that replacing conventional banking with crypto would be unable to support such high-level industrial requirements. Furthermore, experts warn that the adoption of such a system could demoralize international investors and businesses, further deepening the economic challenges the country already faces.
The situation remains fluid as the government prepares for upcoming elections, with international judicial bodies such as the International Court of Justice and the International Criminal Court continuing to evaluate cases related to the conflict. As the threat of further sanctions looms, the debate over how Israel manages its financial ties to the rest of the world remains a critical issue for the nation's future economic stability.





Comments